Polaris Energy Storage News — On August 3, 2026, SNE Research released its semi-annual global lithium-ion energy storage battery shipment report. Data shows global lithium-ion energy storage battery shipments reached 461.3 GWh in H1 2026, surging 71% year-on-year from 269.7 GWh recorded in the same period of 2025.
Driven by rapid industry expansion, the regional landscape, application mix and competitive dynamics of the global energy storage market have all undergone notable shifts.
Global Top 12 Energy Storage Battery Manufacturers by H1 2026 Shipments
Ranked from No.1 to No.12: CATL, EVE Energy, Hithium, BYD, CALB, REPT Batteries, Cornex New Energy, Envision AESC, Gotion High-Tech, Great Power, LG Energy Solution, Samsung SDI.
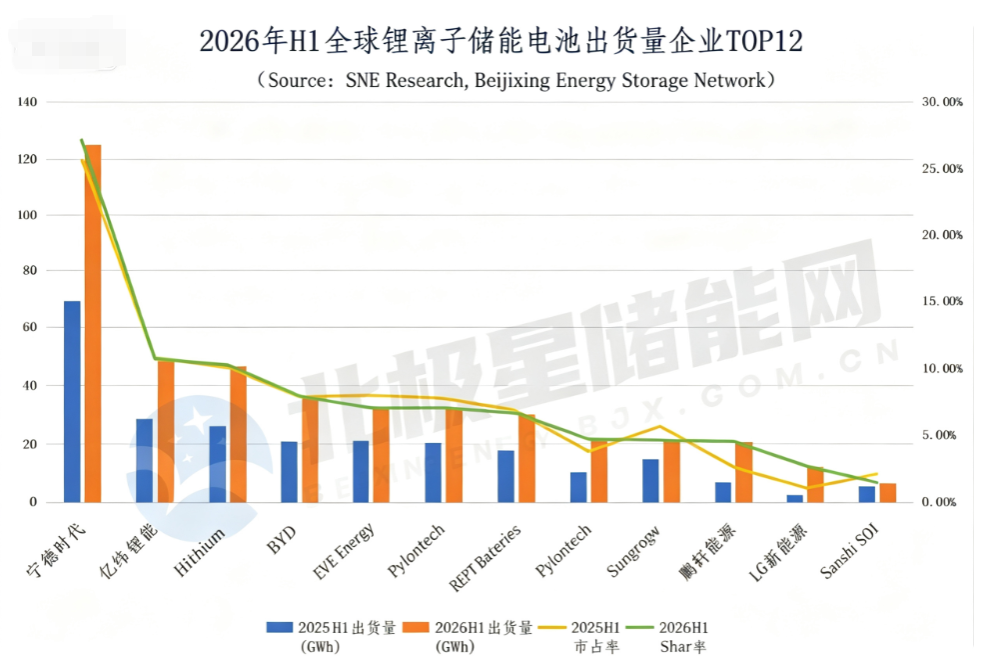
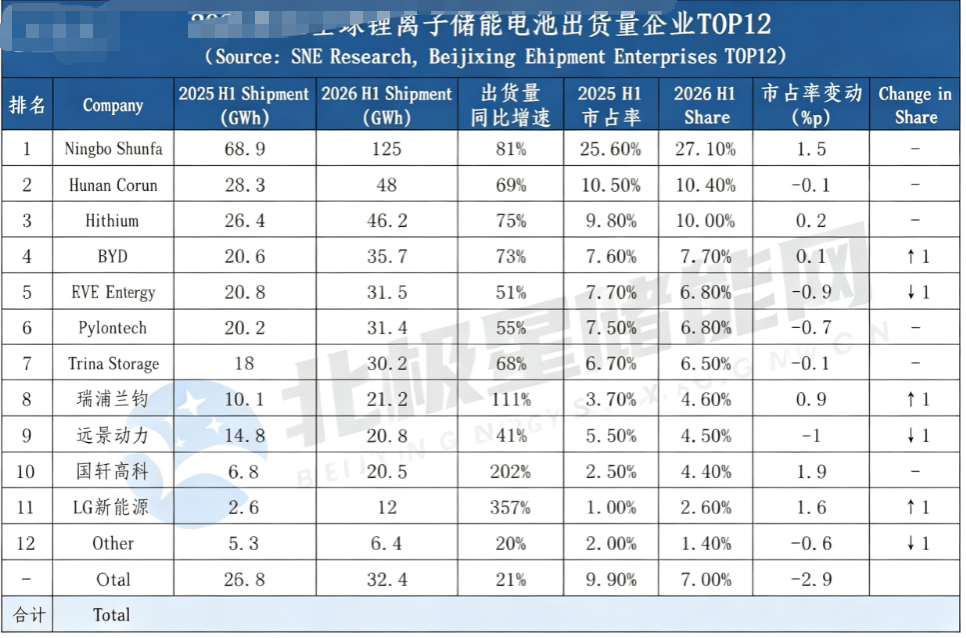
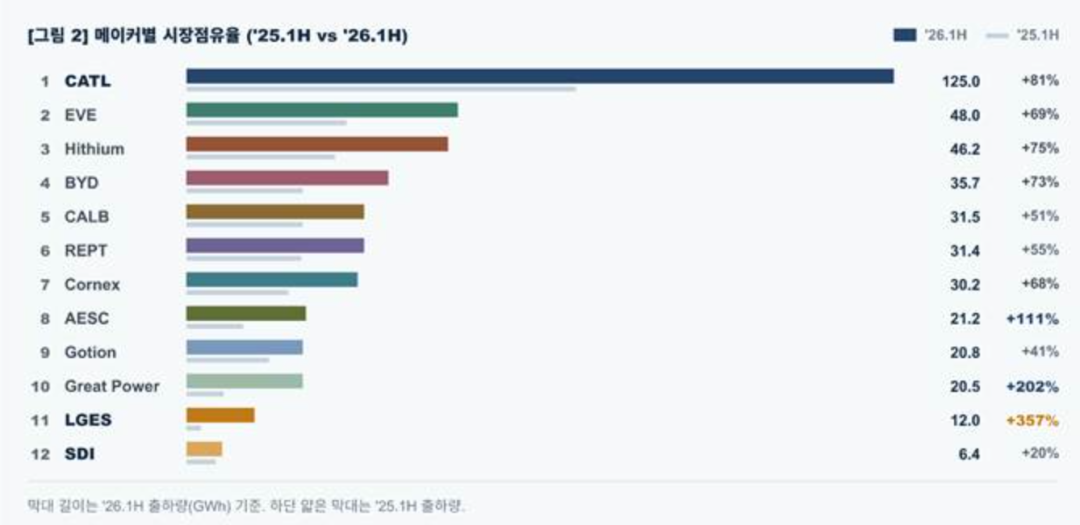
The top 10 players are all Chinese enterprises, with combined shipments of 410.5 GWh, accounting for an overwhelming 89% of the global market.
Core Ranking Highlights
The top three manufacturers together hold a 47.5% combined market share:
CATL: 125 GWh shipments, +81% YoY, 27.1% market share (1st place unchanged)
EVE Energy: 48 GWh shipments, +69% YoY, 10.4% market share (2nd place unchanged)
Hithium: 46.2 GWh shipments, +75% YoY, 10.0% market share (3rd place unchanged)
Three manufacturers recorded triple-digit year-on-year growth: Envision AESC, Great Power and LG Energy Solution.
Two South Korean suppliers occupy the 11th and 12th spots:
LG Energy Solution: 12 GWh shipments, +357% YoY, 2.6% market share
Samsung SDI: 6.4 GWh shipments, +20% YoY, 1.4% market share
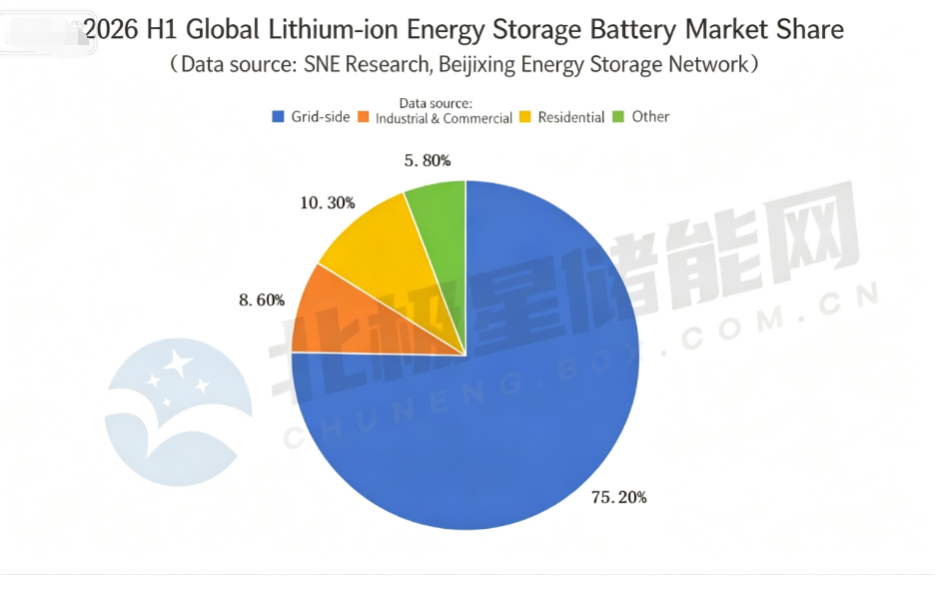
Shipment Breakdown by Application Scenario
Global energy storage demand is split into three core segments with distinct growth momentum:
Grid-Side Storage: 347 GWh shipments (+69% YoY), accounting for 75.2% of total volume — the largest and fastest-growing demand segment.
Commercial & Industrial (C&I) Storage: Shipments rose from 24.9 GWh (H1 2025) to 39.6 GWh (+59% YoY), with steady market expansion.
Residential Storage: Explosive growth recorded, jumping from 20.9 GWh to 47.7 GWh (+128% YoY), with market share climbing from 7.7% to 10.3%.
Market Leader Breakdown by Segment
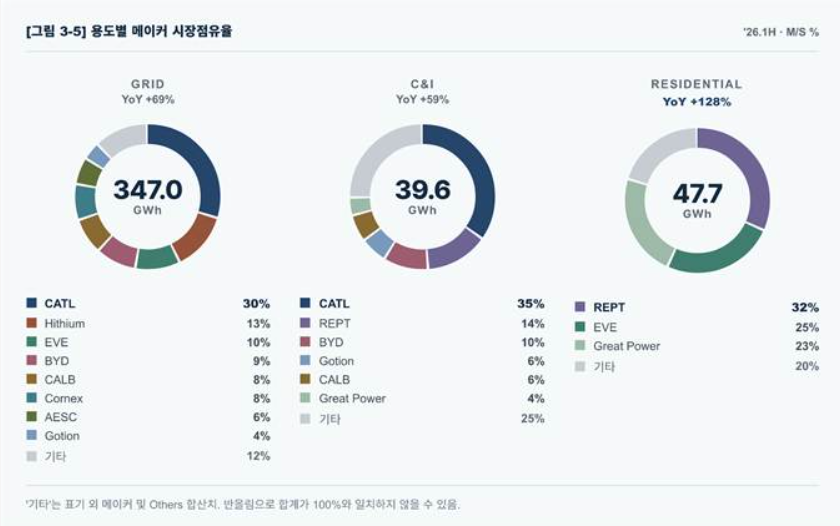
Grid-Side Storage (347.0 GWh)
CATL leads with a 30% share; followed by Hithium (13%), EVE Energy (10%), BYD (9%) and CALB (8%). The top five suppliers capture roughly 70% of the grid-side market, while Cornex, Envision AESC and Gotion High-Tech hold 8%, 6% and 4% respectively.
Commercial & Industrial Storage (39.6 GWh)
CATL maintains top position at 35% market share; REPT Batteries ranks second at 14%, trailed by BYD (10%), Gotion High-Tech (6%) and CALB (6%).
Residential Storage (47.7 GWh)
REPT Batteries dominates residential storage with a 32% share, followed by EVE Energy (25%) and Great Power (23%). These three leaders jointly control 80% of the residential energy storage market.
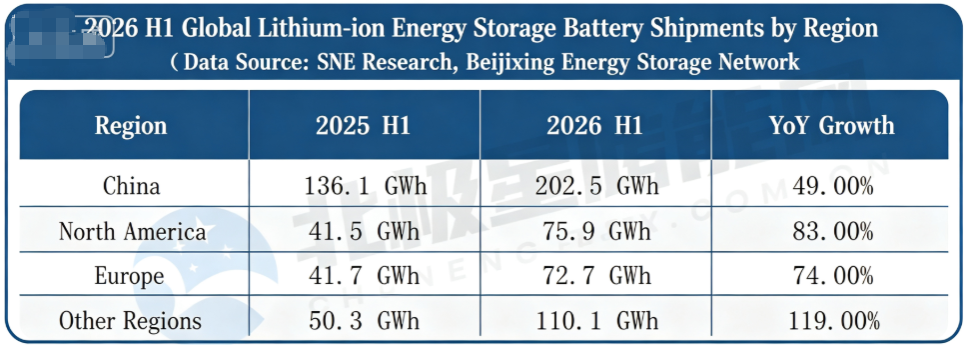
Regional Market Performance
Global energy storage battery shipments show clear diversified regional growth:
China Domestic Market: 202.5 GWh shipments (+49% YoY), still the world’s single largest market, though its share slipped from 50.5% to 43.9% amid faster overseas growth.
North America: 75.9 GWh shipments (+83% YoY)
Europe: 72.7 GWh shipments (+74% YoY)
Other Overseas Regions: 110.1 GWh shipments (+119% YoY), market share up to 23.9% — Middle East, Australia and other emerging markets see outstanding growth.
Rapid demand expansion across Southeast Asia, the Middle East and Latin America drives diversified global demand distribution. In particular, booming construction of AI data centers creates rigid supporting storage demand amid volatile computing power loads, bringing new incremental opportunities to the industry.
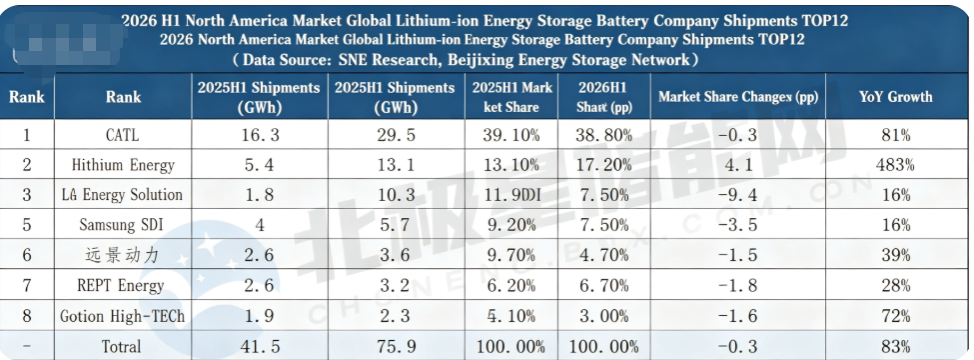
North America Market Detailed Shipment Data
SNE Research released separate statistics for the North American market:
CATL ranks 1st with 29.5 GWh shipments (38.8% market share, +81% YoY)
Hithium takes 2nd place at 13.1 GWh (17.2% share)
LG Energy Solution surges to 3rd: 10.3 GWh shipments, market share up from 4.2% to 13.6%
Samsung SDI shipments rose 16% YoY; its market share fell from 9.7% to 6.1%, with 1.6 GWh dedicated to AI data center storage projects in North America.
Industrial Outlook
Chinese manufacturers remain the core growth engine of the global energy storage sector. Official data from the State Council press conference on July 14 shows lithium batteries, one of China’s three new major export products, posted a 36.5% export volume increase in H1 2026, while total lithium battery-related product exports grew 37.6%. China’s lithium battery import and export volume with Central and Eastern European countries reached RMB 30.01 billion.
Nevertheless, surging overseas demand intensifies competition among leading manufacturers, with fierce rivalry unfolding across product technology iteration, overseas order acquisition and offshore factory deployment.
Source: Polaris Energy Storage Network